Quick Answer
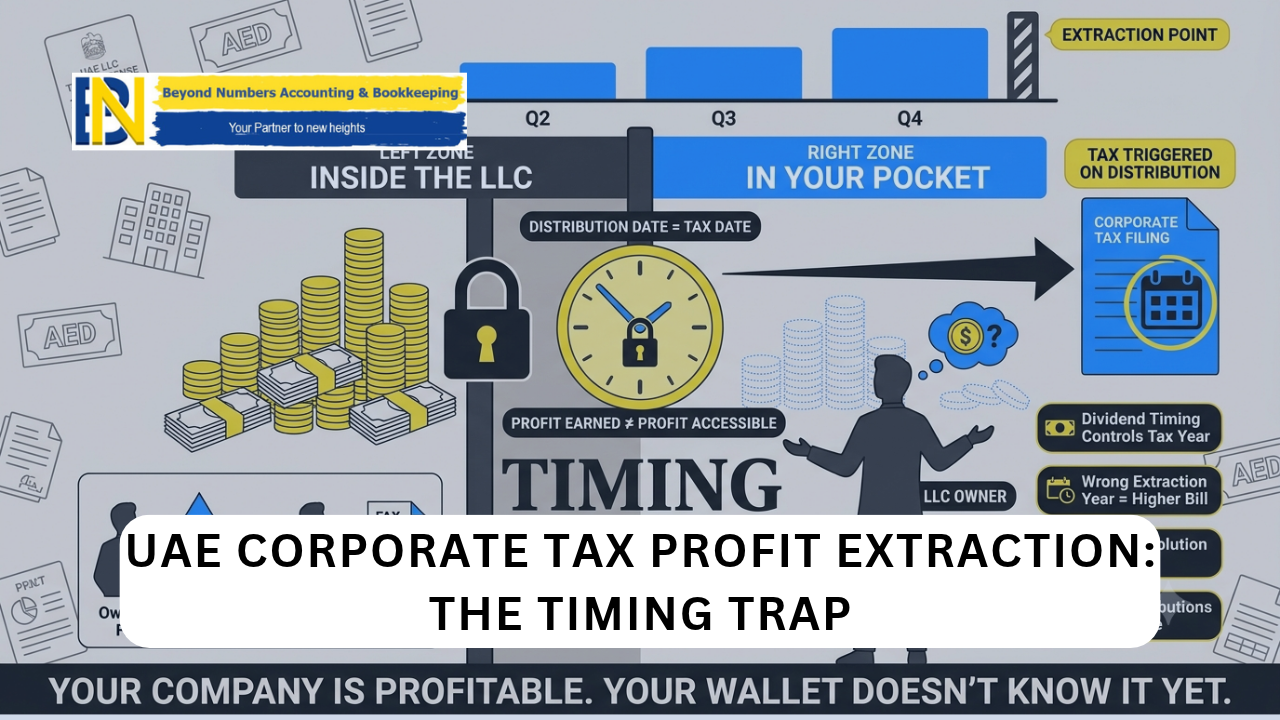
UAE resident companies that pay dividends to UAE resident shareholders benefit from a participation exemption that makes most dividends tax-free at the shareholder level. However, this exemption does not eliminate the company-level corporate tax obligation. A UAE LLC must pay corporate tax on its taxable profit before distributing that profit as dividends. The timing trap arises when business owners withdraw money from their company informally throughout the year, without categorizing it correctly as either a salary or a declared dividend, and without first setting aside corporate tax. The company may then owe corporate tax on profits it has already paid out, creating a liability with no cash left to cover it.
You built the business. The money in the company account feels like your money.
So when you need funds, you transfer them. Sometimes it is a salary. Sometimes it is a loan to yourself. Sometimes it is just a transfer because the company has cash and you need it, and you will work out the paperwork later.
By the end of the year, you have withdrawn AED 1.2 million from the company. The business has not declared any dividends. There is no loan agreement. Some payments were processed through payroll, some were not. The company’s profit and loss statement shows AED 900,000 in net profit before the owner withdrawals are properly accounted for.
The accountant sits down to prepare the corporate tax return. And a problem starts to become clear.
This is the UAE corporate tax profit extraction trap. It is not a problem of whether dividends are taxable. It is a problem of sequence, categorization, and cash. And it is quietly hitting UAE LLC owners who have been running their businesses the same way for years without realizing the rules have changed.
What is the UAE Corporate Tax Position on Dividends?
Before getting to the trap, it helps to understand the basic framework clearly, because the participation exemption that applies to dividends creates a false sense of safety.
Under the UAE Corporate Tax Law, dividends received by a UAE resident company from another UAE resident company are generally exempt from corporate tax at the recipient level under the participation exemption. Additionally, dividends received by a UAE resident individual from a UAE resident company are generally outside the scope of corporate tax at the individual level, because personal investment income is not a taxable business activity for a natural person unless it forms part of a broader business activity.
What this means in plain language is that when a UAE LLC distributes its after-tax profits as a formal dividend to its UAE resident owner, that dividend is typically not taxed again in the owner’s hands.
This is entirely correct. And it has led many UAE business owners to conclude that the profit extraction question is not a tax problem at all. The company makes money, pays its corporate tax, declares a dividend, and the owner receives the money tax-free. That sequence works exactly as intended.
The trap is not in the dividend exemption. The trap is in what happens when the sequence breaks down.
Where the Sequence Breaks Down
The correct sequence for a UAE LLC owner to extract profit looks like this.
The company earns revenue. It deducts legitimate business expenses, including a properly documented and benchmarked salary for the owner if the owner works in the business. The company calculates its taxable profit. It pays corporate tax on that profit at 9% above the AED 375,000 zero-rate band. The remaining after-tax profit is then available for distribution as a dividend, provided the company’s internal governance requirements are met.
Here is how that sequence breaks down in practice for many UAE SME owners.
The owner draws money from the company throughout the year without formal categorization. Some transfers are loosely called salary. Some are called a shareholder loan. Some are simply transfers with no label at all. By year-end, the total withdrawn substantially exceeds what has been formally declared as salary. No corporate tax has been calculated or paid.
The accountant then faces a categorization problem. The undeclared excess withdrawals need to be classified as something. If they are classified as a dividend, the company needs to have declared that dividend, which requires a shareholder resolution and the company to have had sufficient distributable profit at the time. If they are classified as a shareholder loan, the loan needs a written agreement, a market-rate interest charge, and documentation of the repayment terms. If neither of these exists, the classification is contested and the tax treatment is uncertain.
The deeper problem is the cash flow consequence. If the company earned AED 900,000 in taxable profit and the owner already withdrew AED 1.2 million during the year, the company may have insufficient cash remaining to pay its corporate tax bill when the return is due. The tax was owed on the profit. The profit has already been paid out. The tax has to come from somewhere.
The Three Specific Traps Inside the Profit Extraction Problem
There are three distinct ways this problem manifests, and each one has a different tax consequence.
Trap 1: Undocumented drawings treated as salary above the market rate.
If the owner withdrawals are recharacterized as salary, the full amount must pass the connected person salary test. As covered in a separate Beyond Numbers guide, the FTA will assess whether a salary paid to an owner-employee is consistent with what would be paid to an unconnected person in the same role at arm’s length. Salary above that benchmark is non-deductible for corporate tax purposes. The excess is added back to taxable profit, increasing the tax owed. But the cash was already withdrawn. The company now owes more tax on income it spent as salary.
Trap 2: Shareholder loans without interest at a market rate.
If the owner withdrawals are structured as a shareholder loan, the arm’s length principle requires that the loan carries a market rate of interest. A zero-interest or below-market loan to a connected person creates a deemed interest income at the company level. That deemed income is added to the company’s taxable profit even though no cash interest was ever received. The company pays tax on phantom income while the owner has already spent the loaned principal.
Trap 3: Informal dividends declared after the fact without sufficient distributable profit.
A dividend can only be declared from accumulated profit that has already been subject to corporate tax. If an owner tries to retroactively classify year-long withdrawals as a dividend at year-end without the underlying taxable profit having been computed and taxed first, the dividend declaration itself is problematic. It cannot be used to undo the tax obligation. The profit must be taxed before the distribution, not after.
Each of these three traps produces the same underlying outcome: a corporate tax liability that is larger than expected, calculated on amounts the owner believed had already left the company cleanly.
A Real-world Example of the Numbers
Consider a Dubai LLC with one owner who also works as the managing director. During the financial year 2025, the company generates AED 1,500,000 in revenue and spends AED 400,000 on genuine business costs, producing an accounting profit of AED 1,100,000.
Throughout the year, the owner transferred AED 850,000 from the company to their personal account. The transfers were loosely labelled as salary in the company’s bookkeeping, but no benchmarking analysis was done and no payroll formality was followed for most of the payments.
At year-end, the accountant reviews the salary payments. Market benchmarking suggests a reasonable salary for the managing director role would be approximately AED 450,000 to AED 550,000. The excess over AED 550,000, which is AED 300,000, is a non-deductible payment to a connected person.
Taxable income calculation: AED 1,100,000 accounting profit, with the AED 300,000 excess salary added back to arrive at AED 1,400,000 taxable income. After the AED 375,000 zero-rate band, corporate tax at 9% applies to AED 1,025,000. Tax owed: AED 92,250.
Cash position in the company at year-end: limited, because AED 850,000 was withdrawn during the year and ongoing business costs have been paid. The company needs to find AED 92,250 in cash to pay the corporate tax by 30 September 2026.
This is the trap. Not the tax rate. Not the dividend exemption. The absence of a planned, sequenced approach to profit extraction that sets aside corporate tax before the money leaves the company.
How to Structure Profit Extraction Correctly?
The fix is not complicated. It requires discipline about sequence and categorization, applied throughout the year rather than at year-end.
Formalize the owner salary at the beginning of the year. Set a salary figure for the owner-employee that is consistent with the market rate for the role. Run it through payroll consistently every month. This creates a clear, defensible salary expense that reduces corporate taxable profit and provides the owner with a predictable monthly income.
Keep company cash and personal cash completely separate. All company money stays in the company account. All personal expenses are paid from the owner’s personal account using the salary received. No informal transfers from company to personal account for unspecified purposes.
Estimate the corporate tax liability quarterly. Using the actual profit and loss figures each quarter, calculate the approximate corporate tax that will be owed for the year. Set that estimated amount aside in a designated reserve or a separate savings account. Do not treat it as distributable profit.
Declare dividends formally and from after-tax profit only. At year-end, after the financial statements are prepared and the corporate tax liability is calculated and reserved, the remaining after-tax profit is available for a formal dividend declaration. This requires a shareholder resolution documenting the dividend, the amount per share, and the declaration date. The dividend is then paid from the company account to the owner’s personal account as a documented distribution.
If the owner needs cash above the salary before year-end, structure it as a formal shareholder loan with a written agreement, a market rate of interest, and a documented repayment schedule. Keep it modest and ensure it is repaid before year-end if possible.
6-Question Profit Extraction Health Check for UAE LLC Owners
Answer these honestly for the current financial year.
- Has the owner salary been formally documented, benchmarked against the market rate for the role, and processed consistently through payroll?
- Are all owner withdrawals from the company account either (a) formal salary payments or (b) documented shareholder loans with interest?
- Has the company estimated its corporate tax liability for the current year and set aside sufficient cash to cover it?
- Is the company’s cash balance sufficient to pay the estimated corporate tax in full without relying on future revenue?
- Are formal shareholder resolutions prepared for any dividends declared or planned?
- Has a connected person salary benchmarking analysis been completed and retained on file?
A yes to all six means the profit extraction structure is sound. Any no is a gap that needs to be addressed before year-end, not after.
Frequently Asked Questions
Q. Is a dividend from a UAE LLC taxable at the shareholder level?
A. Dividends received by a UAE resident individual from a UAE resident LLC are generally outside the scope of corporate tax for the individual, because personal investment income does not constitute a business activity for natural persons. The key condition is that the company has first paid corporate tax on the underlying profit before distributing it.
Q. Can an LLC owner take a salary instead of dividends to reduce corporate tax?
A. Yes, within limits. A salary paid to an owner who genuinely works in the business is a deductible expense, subject to the connected person arm’s length benchmark. A salary that is set above the market rate for the role, purely to minimise the company’s taxable profit, will have the excess portion added back as a non-deductible amount.
Q. What is the connected person arm’s length test for owner salaries?
A. The FTA assesses whether the salary paid to an owner-employee is consistent with what an unconnected third party in the same role, at the same company size and industry, would be paid. If the company pays its owner AED 1 million per year for a role that the market would pay AED 500,000 for, AED 500,000 of that salary is non-deductible.
Q. What happens if owner withdrawals have already been made informally throughout the year?
A. The first step is categorisation: determine how much of the withdrawals represents a defensible market-rate salary and how much needs to be treated as either a shareholder loan or a dividend. If the remaining year-end profit is sufficient to support a dividend declaration after corporate tax is reserved, a formal dividend resolution can be prepared. Any amount that cannot be categorised as salary or a declared dividend from taxable profit should be treated as a shareholder loan with documentation and interest.
Q. Does a small UAE LLC with no employees other than the owner need to pay the owner a salary?
A. There is no legal requirement to pay an owner salary. An owner who does not work in the business can take distributions purely as dividends. An owner who does work in the business should receive a salary that reflects the market value of their contribution, because the absence of any salary where real work is performed can itself attract scrutiny on whether the profit figure is correctly stated.
You do not have to Navigate This Alone
For most UAE LLC owners, the question of how to take money out of the company in a tax-efficient, correctly sequenced way is not something they were taught when they set up the business. The old habits of treating the company account as a personal account worked well before corporate tax. They create real problems now.
That is exactly where Beyond Numbers comes in.
Beyond Numbers helps UAE LLC owners structure their profit extraction correctly from the start of each financial year: setting the right salary, reserving for corporate tax, preparing formal dividend resolutions, and ensuring that every dirham taken out of the company is properly categorised, documented, and defensible if the FTA asks questions.
If you are currently taking money out of your company without a clear, documented structure for how it is classified and taxed, the right time to fix that is before this financial year closes, not after the return is due.
Talk to Beyond Numbers today. Our team will review your current profit extraction approach, calculate the corporate tax liability on your actual year-to-date position, and put the right structure in place for the rest of this year and every year going forward.
This article reflects UAE Corporate Tax rules as of November 2026 and is for general guidance only. For advice specific to your business, speak with the Beyond Numbers tax team directly.